As an agent in Florida, you already know the first question a frontline-worker buyer asks about this program: how much money can they actually get toward buying a home, and what does that money cover? That is the conversation this guide prepares you for.
The Florida Hometown Heroes Housing Program provides down payment and closing cost assistance to first-time income qualified homebuyers serving the community in which they work, and the exact amount depends on the program’s current rules and the buyer’s first mortgage loan amount.
At Charles Rutenberg Realty, our agents work with Florida buyers across Clearwater and Tampa Bay who hear about Hometown Heroes and assume everyone gets the full $35,000. That is the most common misunderstanding we see. Most buyers fall somewhere in the middle because the assistance is calculated as a percentage of the loan, with a floor and a ceiling. One of the things that makes you the expert your clients trust is your ability to explain that clearly.
The Florida Housing Finance Corporation administers the program, and we cite it as the source for every program rule. You can confirm current terms on the Florida Housing Finance Corporation’s Hometown Heroes program page. Program details and available funding change frequently, so check the income limits, assistance terms, funding availability and other details before sharing program information with buyers and sellers.
We checked all information in this article as of October 2026 using publications provided by the Florida Housing Finance Corporation (links in each section of this article). Buyers should confirm eligibility for participation (such as occupation), assistance amount and other details with a participating loan officer.
How Much Down Payment Assistance Hometown Heroes Offers
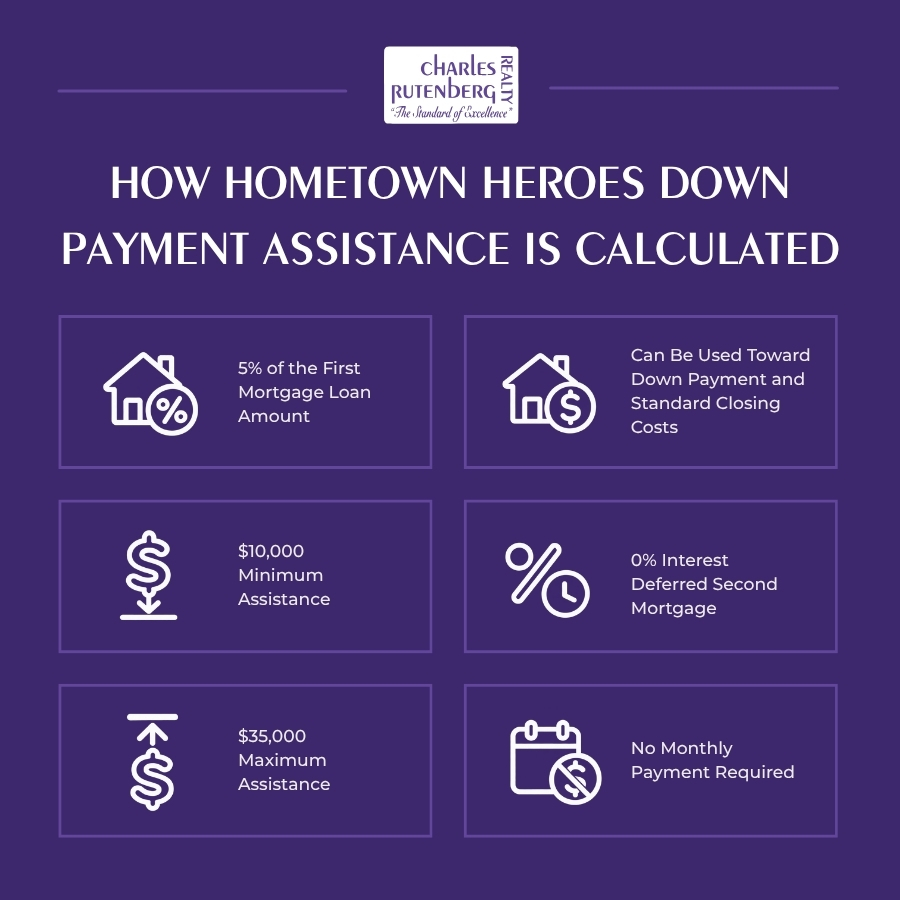
Assistance will be 5% of the 1st mortgage loan amount. The minimum amount of assistance available is $10,000 and the maximum assistance available is $35,000. So if the loan amount is less than or equal to $200,000, they’ll receive $10,000. If the loan is for a higher amount, assistance will be available at a higher amount, up to $35,000.
Down payment and closing cost assistance is offered as a second mortgage with 0% interest that does not amortize. No monthly payment is required. Payment is due if the home is sold, refinanced, if title is transferred to someone else or if the homebuyer stops living in the home as their primary residence. In plain terms, it’s a deferred second mortgage. Buyers don’t pay it down each month, but it isn’t forgiven either. The sections below go deeper on the math and the rules.
How Much Can Hometown Heroes Help With a Home Purchase?
The calculation is simple. Take the buyer’s first mortgage loan amount, multiply by 5%, then apply the floor and the cap. If 5% comes out below $10,000, the buyer still receives the minimum. If 5% comes out above $35,000, the assistance is capped there.
Here’s how that plays out across a few hypothetical loan amounts. These are illustrations only, and county loan limits apply, so confirm each scenario against current limits.
|
First Mortgage Loan Amount |
5% of Loan | Assistance Received |
| $180,000 | $9,000 | $10,000 (minimum applies) |
| $300,000 | $15,000 | $15,000 |
| $500,000 | $25,000 | $25,000 |
| $750,000 | $37,500 | $35,000 (maximum applies) |
Assistance may be applied toward the down payment and standard closing costs.
For a buyer, that means real cash they don’t have to bring to the table. For instance, in a FHA purchase, the program is meant to assist in paying for the down payment and some of the closing costs, which is precisely what holds back potential buyers from renting longer than they’d like. The goal is to make homeownership more affordable for eligible workers who serve the community in which they work.
Many frontline-worker buyers think they’ll receive $35,000 in assistance to put down on their home purchase when applying through the Hometown Heroes program. So make sure you’re sharing accurate information with your buyers.
Who Qualifies for Hometown Heroes Down Payment Assistance?
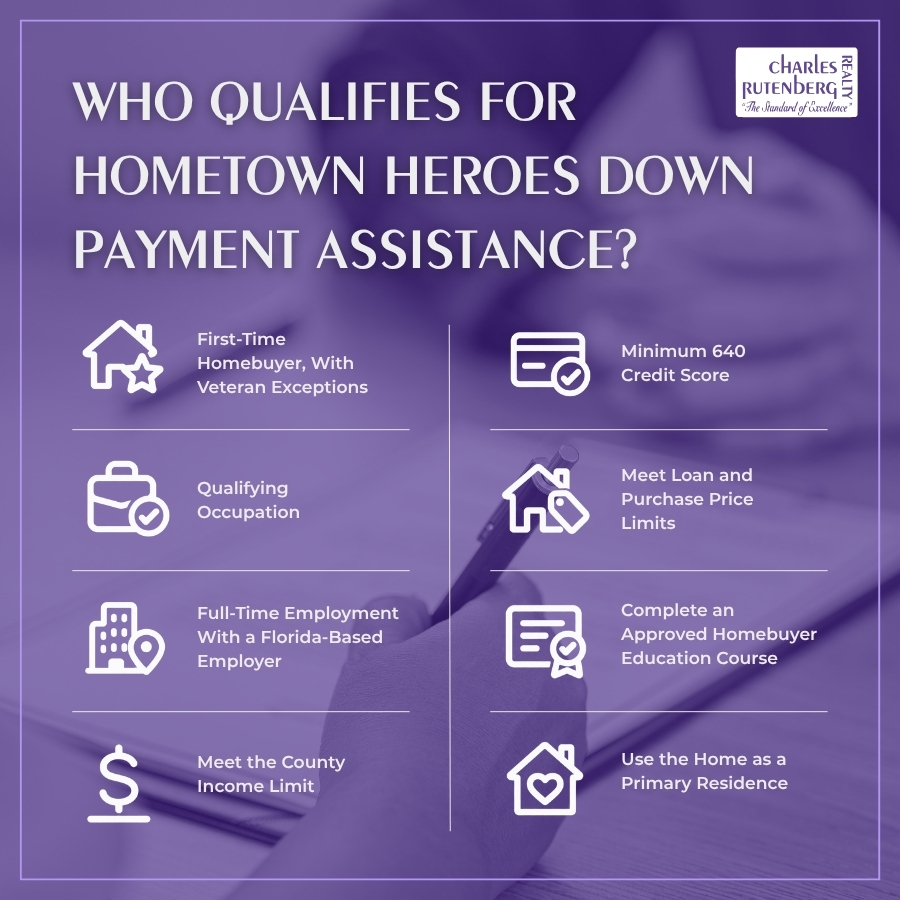
Eligibility is where buyers get tripped up most often, so walk through each requirement with them early. To participate in Hometown Heroes, homebuyers must meet each of the following criteria.
First-Time Homebuyer (With Veteran Exceptions)
Generally speaking, homebuyers may not have owned a primary residence within the past 3 years to qualify as a first-time homebuyer for this program, with exceptions for veterans, active military and buyers purchasing in federally designated targeted areas.
Qualifying Occupation
The occupation criteria of the Hometown Heroes Program include full-time health care workers, school staff members, first responders, public safety workers, court employees and child care workers, plus veterans and active duty or reserve servicemembers. Buyers unsure whether their role counts should check the official occupation list and confirm with a participating loan officer.
Full-Time Employment With a Florida-Based Employer
Employment criteria in this program are that homebuyers be employed full-time by a Florida based employer. Veterans can work for any Florida based company (not occupation-specific like other program participants) as long as it is full-time employment.
Income Limit
Household income cannot exceed the limit for the county in which the home is located, which Florida law caps at 150% of the state or local median income, whichever is greater. Florida Housing publishes the table of income limits for every county.
One point our agents flag constantly: veteran buyers using a VA loan are still subject to the income limit in the county in which the home is located. Make sure your veteran buyers are informed of the county’s income limit before starting the search for their new home.
Minimum Credit Score
The minimum FICO score for this program is 640. Buyers that are close to this line should talk with a loan officer about options for increasing their credit score before applying. DTI (debt to income ratio) with an automated underwriting decision is maxed out at 50%.
Loan and Purchase Price Limits
County loan and income limits vary across Florida. Limits in Hillsborough and Pinellas counties differ from those in Miami-Dade, for example. There isn’t just one limit for the state of Florida and the limits change periodically. So make sure you’re pulling the most up-to-date limits from the Florida Housing website.
Homebuyer Education Course
One of the borrowers has to complete a homebuyer education course (prior to closing) approved by Florida Housing unless the purchaser is a veteran, active duty military member or member of the Reserves or National Guard. That exemption doesn’t apply to HFA Advantage conventional loans, and exemptions may vary. So it’s best to double-check with the lender.
The Home Must Be Your Primary Residence
Similar to most down payment assistance programs in Florida, when buyers purchase a home through Hometown Heroes, it must be their primary residence. Vacation homes, second homes and investment properties are not allowed with this program. It’s an owner-occupied, primary residence program only.
What Loan Types Can Be Used With Hometown Heroes?
The assistance works with four first mortgage loan program options: conventional, FHA, VA or USDA. It’s important for real estate agents to have a working knowledge of the various loan options, what Hometown Heroes assistance pays toward for each loan type and what income limits borrowers will have to fall under to be eligible.
The assistance comes in the form of a 0% interest, deferred payment second mortgage, so the Hometown Heroes loan sits behind the first mortgage no matter which loan type the buyer chooses. The rate for the 30-year fixed rate first mortgage is determined by Florida Housing. Each of the 4 available loan types (FHA, VA, USDA and conventional) has its own advantages.
FHA Loans
FHA loans are a strong fit for buyers with less than stellar credit. Hometown Heroes funds can pay for a majority of the down payment (FHA down payments can currently be as low as 3.5%) as well as closing costs, layered behind the fixed rate mortgage.
VA Loans
Contrary to what many think, veterans and active duty military are subject to income limits for Hometown Heroes, but VA is one of the strongest loans to use with the program since down payments are often $0. Hometown Heroes assistance can then be used for closing costs.
USDA (Rural Development)
Buyers that are purchasing in a USDA eligible, rural area of Florida can take advantage of $0 down USDA financing plus use the Hometown Heroes program for closing costs.
Conventional Loans (Freddie Mac HFA Advantage® Loans)
Hometown Heroes can also be used by buyers with higher credit looking to receive assistance towards their down payment and potentially save on mortgage insurance with a conventional loan.
How To Apply for the Hometown Heroes Program
First, check to see if your buyer’s occupation is eligible by going to the Florida Housing Finance Corporation website. Borrowers must be employed full-time at the time of closing in one of the eligible occupations.
After determining your buyer’s occupation and income fall under the guidelines for their county, here are the steps to apply:
- Get pre-approved by a Florida Housing participating loan officer (find one with the Lender and Real Estate Agent Locator)
- Complete a Florida Housing approved homebuyer education course (may be waived in some circumstances)
- Get help from a Realtor® and tour homes within the loan limits for their county
Hometown Heroes funding is released in rounds and can be fully reserved in less than two months. The most recent funding opportunity opened July 13, 2026 and came with $50 million in available and approved funding.
It’s always best to get buyers pre-approved for financing before touring homes. It gives you an idea of exactly how much house they can spend on, narrows your property search, gets the transaction moving quicker and makes sellers more confident in an offer. Buyers applying for special programs like Hometown Heroes should get started on the process as soon as possible because when funding does become available, it doesn’t always last.
Build Your Florida Career With Charles Rutenberg Realty
Hometown Heroes is a great resource you can tap into to help your buyer clients and show that you know the ins and outs of all that is offered to make Florida home ownership the best it can be. Check out How to Become a Local Real Estate Market Expert for more ways you can become the go-to local expert.
Founded in 2000, Charles Rutenberg Realty is now home to more than 2,100 real estate professionals who have chosen our agent-first model because it fits their business and lifestyle goals. At Charles Rutenberg Realty, agents receive low fees, keep 100% commission and have access to a wide range of training, tech and marketing resources to help build a thriving, referral based business.
If you’re interested in learning more, schedule a call with our broker or apply to join our team today to see what an agent-first brokerage could do for your real estate career. You can also call our Clearwater, FL office at (727) 538-9200.
Our agents and staff love helping buyers and sellers in every step of their Florida real estate transaction. If you’re thinking about buying a home or considering selling your current home, connect with one today.
The Charles Rutenberg Realty Team