As a Florida Realtor®, you help home buyers make good decisions in local markets. One of those decisions could be using a down payment and closing cost assistance program.
The Florida Hometown Heroes Housing Program, administered by the Florida Housing Finance Corporation, is one of those programs available to buyers. But what is Hometown Heroes, who qualifies, and how can you help your buyer? Here’s your Realtor® guide to the Hometown Heroes housing program.
At Charles Rutenberg Realty, our agents work with Florida buyers every day. Your role is specific: spot potential eligibility, describe the program accurately, and connect the buyer with a participating loan officer.
What Florida Realtors Should Know About Hometown Heroes
Originally introduced by the Florida Legislature in 2022, the Florida Hometown Heroes Loan Program is a down payment assistance (DPA) loan program available to help certain professionals throughout the state of Florida who have a steady income but lack the financial means to purchase a home due to upfront down payment and closing costs.
This down payment assistance program, which is administered by the Florida Housing Finance Corporation, offers eligible buyers the opportunity to receive up to $35,000 to help offset the cost of their down payment and/or closing costs.
Funding opens and closes by program year, so there’s plenty more information Florida Realtors® should know about the program to better help their home buyer clients and stay on top of changes from one funding cycle to the next.
Eligibility, income limits, and loan limits shift by county and program year, so confirm them against current Florida Housing guidelines. You help identify the opportunity and make the introduction, while the participating lender determines whether the buyer qualifies.
What Is the Hometown Heroes Program in Florida?
The Hometown Heroes Housing Program is state-backed in Florida, designed to help make it more affordable for certain workforce professionals to purchase a primary residence.
While originally limited to professions such as healthcare workers, teachers, first responders/law enforcement, and members of the Florida National Guard, the eligible employment list has changed by program year. The 2026 program covers groups such as health care workers, school staff, first responders, public safety and court employees, child care workers, veterans, and service members. Your clients’ eligibility also depends on where they work.
The Hometown Heroes down payment assistance program is offered through a participating lender as a deferred loan paired with a 30-year, fixed-rate mortgage used to purchase the buyer’s primary residence.
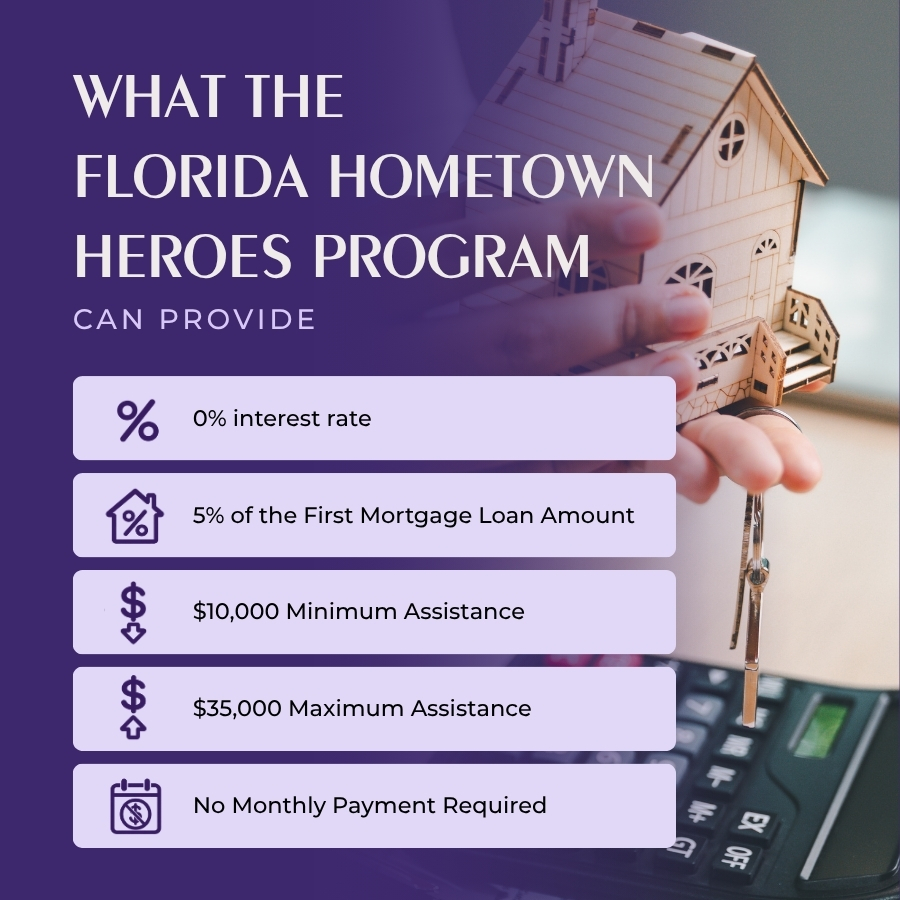
The Hometown Heroes second mortgage provides:
- 0% interest rate
- 5% of the total first mortgage loan amount (minimum assistance of $10,000; maximum assistance of $35,000)
- No monthly payment required
The deferred second mortgage would have to be repaid at:
- Sale of property
- Refinance of first mortgage
- Deed transfer
- When the home is no longer the borrower’s primary residence
Who Qualifies for Hometown Heroes?
The Hometown Heroes DPA program was made for steady-income professionals who struggled to save for a down payment or cover the costs associated with a mortgage closing, such as active military, veterans, or certain professionals looking to purchase their first home.
Originally limited to frontline workers in specific sectors, eligibility for Hometown Heroes has changed across program years. However, at least one buyer in the transaction would need to:
- Be a full-time employee of a Florida employer with a business location in the state
- Live and work in Florida
*Fully remote jobs are not eligible to use this assistance. Depending on the employer, hybrid employees may need to check in at a physical location within Florida.
Florida veterans who received an honorable discharge (and some other situations) and live and work full-time within the state may apply even if they’ve owned a home in the past, bypassing the first-time homebuyer requirement.
That said, none of this is yours to rule on. Specific eligibility, income limits, and requirements change, so confirm them against current Florida Housing guidelines and let the participating lender make the call.
How Does the Hometown Heroes Program Work in Florida?
The path from interest to closing follows a predictable set of steps. Walking a buyer through it at a high level, while leaving the qualifying to the lender, is exactly where a strong agent earns trust.
Identifying the Program as a Fit
When a buyer mentions a qualifying line of work, like nursing, teaching, or public safety, that’s your cue to mention the Florida Hometown Heroes Housing Program as something worth exploring. You’re not promising anything yet. You’re pointing out an option they may not know exists.
Determining Eligibility Through a Lender
The Hometown Heroes housing program is a Florida down payment assistance option tied to an approved first mortgage, including FHA, VA, USDA, or Conventional. It’s a deferred second mortgage to help eligible buyers with down payment and closing costs. In the 2025 funding cycle, the average assistance was about $16,000 per buyer.
Buyers could be steady on their feet with income but need help in other areas, like the cash it takes to close. Hometown Heroes could help connect the dots.
Eligibility for this Florida Housing program is determined by lenders. Buyers will need a participating loan officer to apply for and reserve program funds, subject to Florida Housing guidelines in effect at that time. The program doesn’t guarantee funds, even for buyers who qualify.
Here are some key elements for qualifying for the Florida Hometown Heroes Program:
- Being employed full-time in a profession serving Florida’s workforce or being an active-duty military member or a veteran;
- Meeting the county’s income limits
- Meets other qualifications, like a 640 minimum credit score; and
- Completes a homebuyer education course (HUD-approved)
Find more Hometown Heroes program details and Florida Housing Program income limits here.
Selecting a Participating Loan Officer
Not every mortgage professional offers this loan program, so buyers need to select one participating in the Hometown Heroes program. Keep a list of Florida Housing-approved Hometown Heroes lenders on hand to help clients get the ball rolling quickly, which is especially helpful in a competitive market like Clearwater.
Obtaining the First Mortgage
The first mortgage, like an FHA or Conventional loan, follows typical timelines to get pre-qualified or pre-approved. After that, the loan officer applies and reserves Hometown Heroes funds contingent on guidelines at that time.
Once a buyer finds a home and makes an offer, the loan officer orders an appraisal and begins the underwriting process. Then the closing will include two loans: the first mortgage and the Hometown Heroes deferred second mortgage.
Applying the Assistance to the Purchase
At closing, the approved funds go toward the buyer’s down payment and closing cost needs, structured as that deferred second mortgage. The exact amount depends on the size of the first mortgage and current program guidelines.
How Long Will the Hometown Heroes Program Last?
Never treat the program’s funding or terms as permanently available or unchanged. The program runs in funding cycles, and money can be committed quickly.
How much assistance will Florida have for Hometown Heroes? In July 2023, the Florida Legislature provided $100 million for Hometown Heroes funds, all of which was spoken for within 2 months. Over 6,400 families used this down payment assistance program to purchase a home.
The good news is the Florida 2026-2027 budget includes $50 million for the program for down payment and closing costs assistance. However, the state sets new allocations each year, so funding can change. So if you have questions about the Hometown Heroes Florida program, reach out to a participating lender.
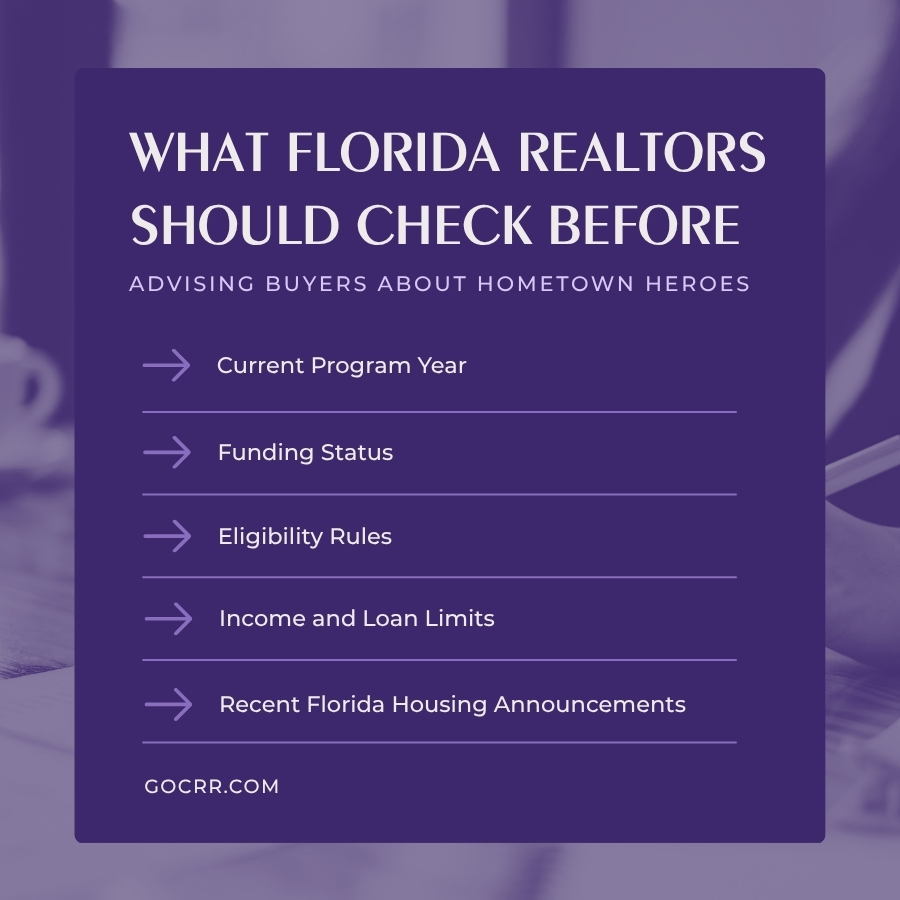
Before you advise a buyer, check the current program year, funding status, eligibility rules, income and loan limits, and any recent Florida Housing announcements.
How Realtors Can Help Buyers Use Hometown Heroes
As a Realtor®, you can educate yourself on DPA programs offered within your local market that your home buyer clients may be eligible to use. Though not limited to Realtors®, DPA programs like Hometown Heroes can be a huge selling point to help your home buyer clients win in a competitive real estate market.
Though your clients would work with a participating lender to determine their final eligibility, it’s helpful for Florida Realtors® to have a firm understanding of how the Hometown Heroes DPA Program works and share accurate information with their clients.
It’s always changing
Details surrounding the Hometown Heroes Program, such as income and loan limits, eligible counties and professions, and overall available funds may change from year-to-year and county-to-county. We highly recommend reviewing current program guidelines on the Florida Housing website, as terms can change quickly and Realtors® should refrain from over-promising on specifics.
Know when to hand off
As mentioned, you’re not responsible for determining your buyers’ eligibility in the Hometown Heroes DPA program or reserving program funds for them. Though Realtors® can help identify potential candidates for assistance programs and provide an overview, a participating lender is the best resource to speak with for complete qualification and assistance.
You know full-time nurses, teachers, public safety officials, and other professionals are important to our local communities and may qualify to buy a home through Hometown Heroes. You know financing is often the hardest piece for home buyers, and a program like Hometown Heroes could help your clients achieve their Florida homeownership dream.
Your buyer’s loan officer is the best resource for program details and loan qualification. Realtors® shouldn’t provide legal, tax, or financial advice, or loan qualification, and shouldn’t overpromise assistance amounts or program timelines, either. Point buyers to the appropriate licensed professional when those questions come up. Program terms and guidelines can and do change.
Florida down payment assistance programs
Florida down payment assistance programs can change, and so can available funds. It’s important to provide clients the most accurate information available. It saves you time, and they’ll count on you for more helpful resources in the future.
Florida down payment assistance programs, like the Hometown Heroes DPA loan program, can be helpful for buyers looking to save some money upfront. Though Realtors® can’t offer specifics, it’s a great idea to be on top of resources your buyers can leverage. That knowledge makes your expertise all the more valuable to your clients (and helps them feel at ease when the real estate market is moving faster than we can blink).
Knowing programs like this well is part of being the agent buyers rely on. If you want to deepen that edge, our guide on how to become a local real estate market expert pairs well with this kind of specialized knowledge.
Grow Your Florida Business With Charles Rutenberg Realty
Understanding local market dynamics and buyer financing options helps you win business in the Tampa Bay area and beyond. Become the agent clients count on and refer their friends and family to.
At Charles Rutenberg Realty, we support agents like you with the best tech and tools, training and education, marketing resources, and a collaborative environment. Founded in 2000, our Florida brokerage is one of the largest and most respected in Florida and home to over 2,100 Florida real estate professionals, and growing. Enjoy low fees and a 100% commission structure, so you keep what you make.
Schedule a call with our broker or apply to join Charles Rutenberg Realty and grow your business the right way.
Setting The Standard For Real Estate Excellence.